Step-by-Step Guide to E-Filing IRS Form 8868 for Nonprofits
· Last reviewed · 3 min read
If your nonprofit needs more time to file Form 990-EZ or Form 990, Form 8868 gets you an automatic 6-month extension. This guide walks through e-filing it with 990.tax and lists the rules to check first.
Before you start
- Know your due date. File Form 8868 by the due date of the return you are extending: the 15th day of the 5th month after your tax year ends, moved to the next business day if it falls on a weekend or legal holiday. For a June 30, 2026 year end, that is November 16, 2026, because November 15 is a Sunday. See Form 8868 due dates.
- One extension per return. The IRS allows a single 6-month extension for each type of return for a tax year.
- Not for Form 990-N. You cannot use Form 8868 to extend the e-Postcard. Form 990-N has no extension, and the IRS does not charge a penalty for filing it late.
- Not an extension to pay. Form 8868 does not extend the time to pay tax.
990.tax files Form 8868 to extend Form 990 or Form 990-EZ. The fee is $9.99 per filing, with no subscription. You pay after the form is completed and signed, before it is sent to the IRS.
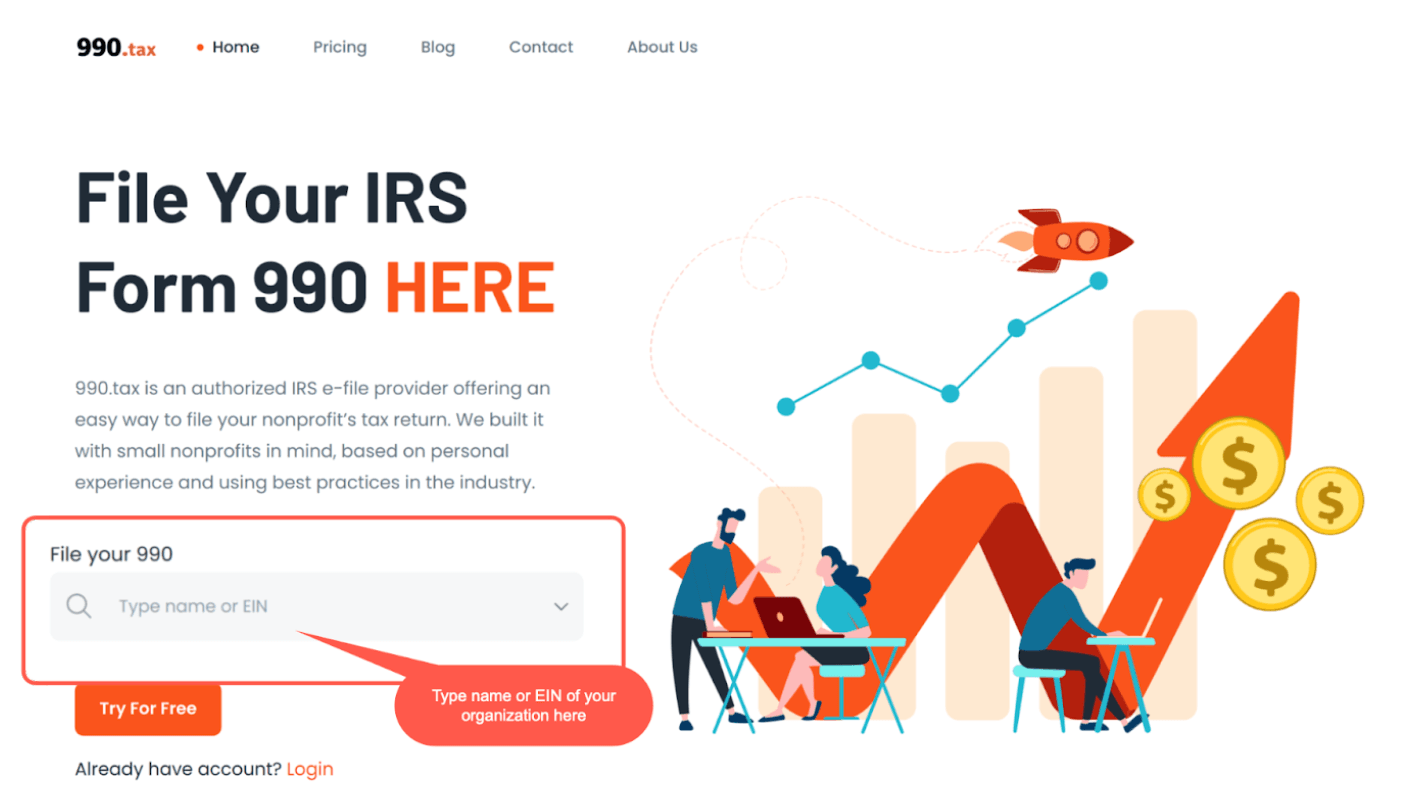
Step 1: Go to 990.tax. If you have an account, log in. If not, start typing your organization's name or EIN to create one.
Step 2: Basic information. Enter or confirm your organization's legal name, EIN and address. Use the name and EIN exactly as the IRS has them.
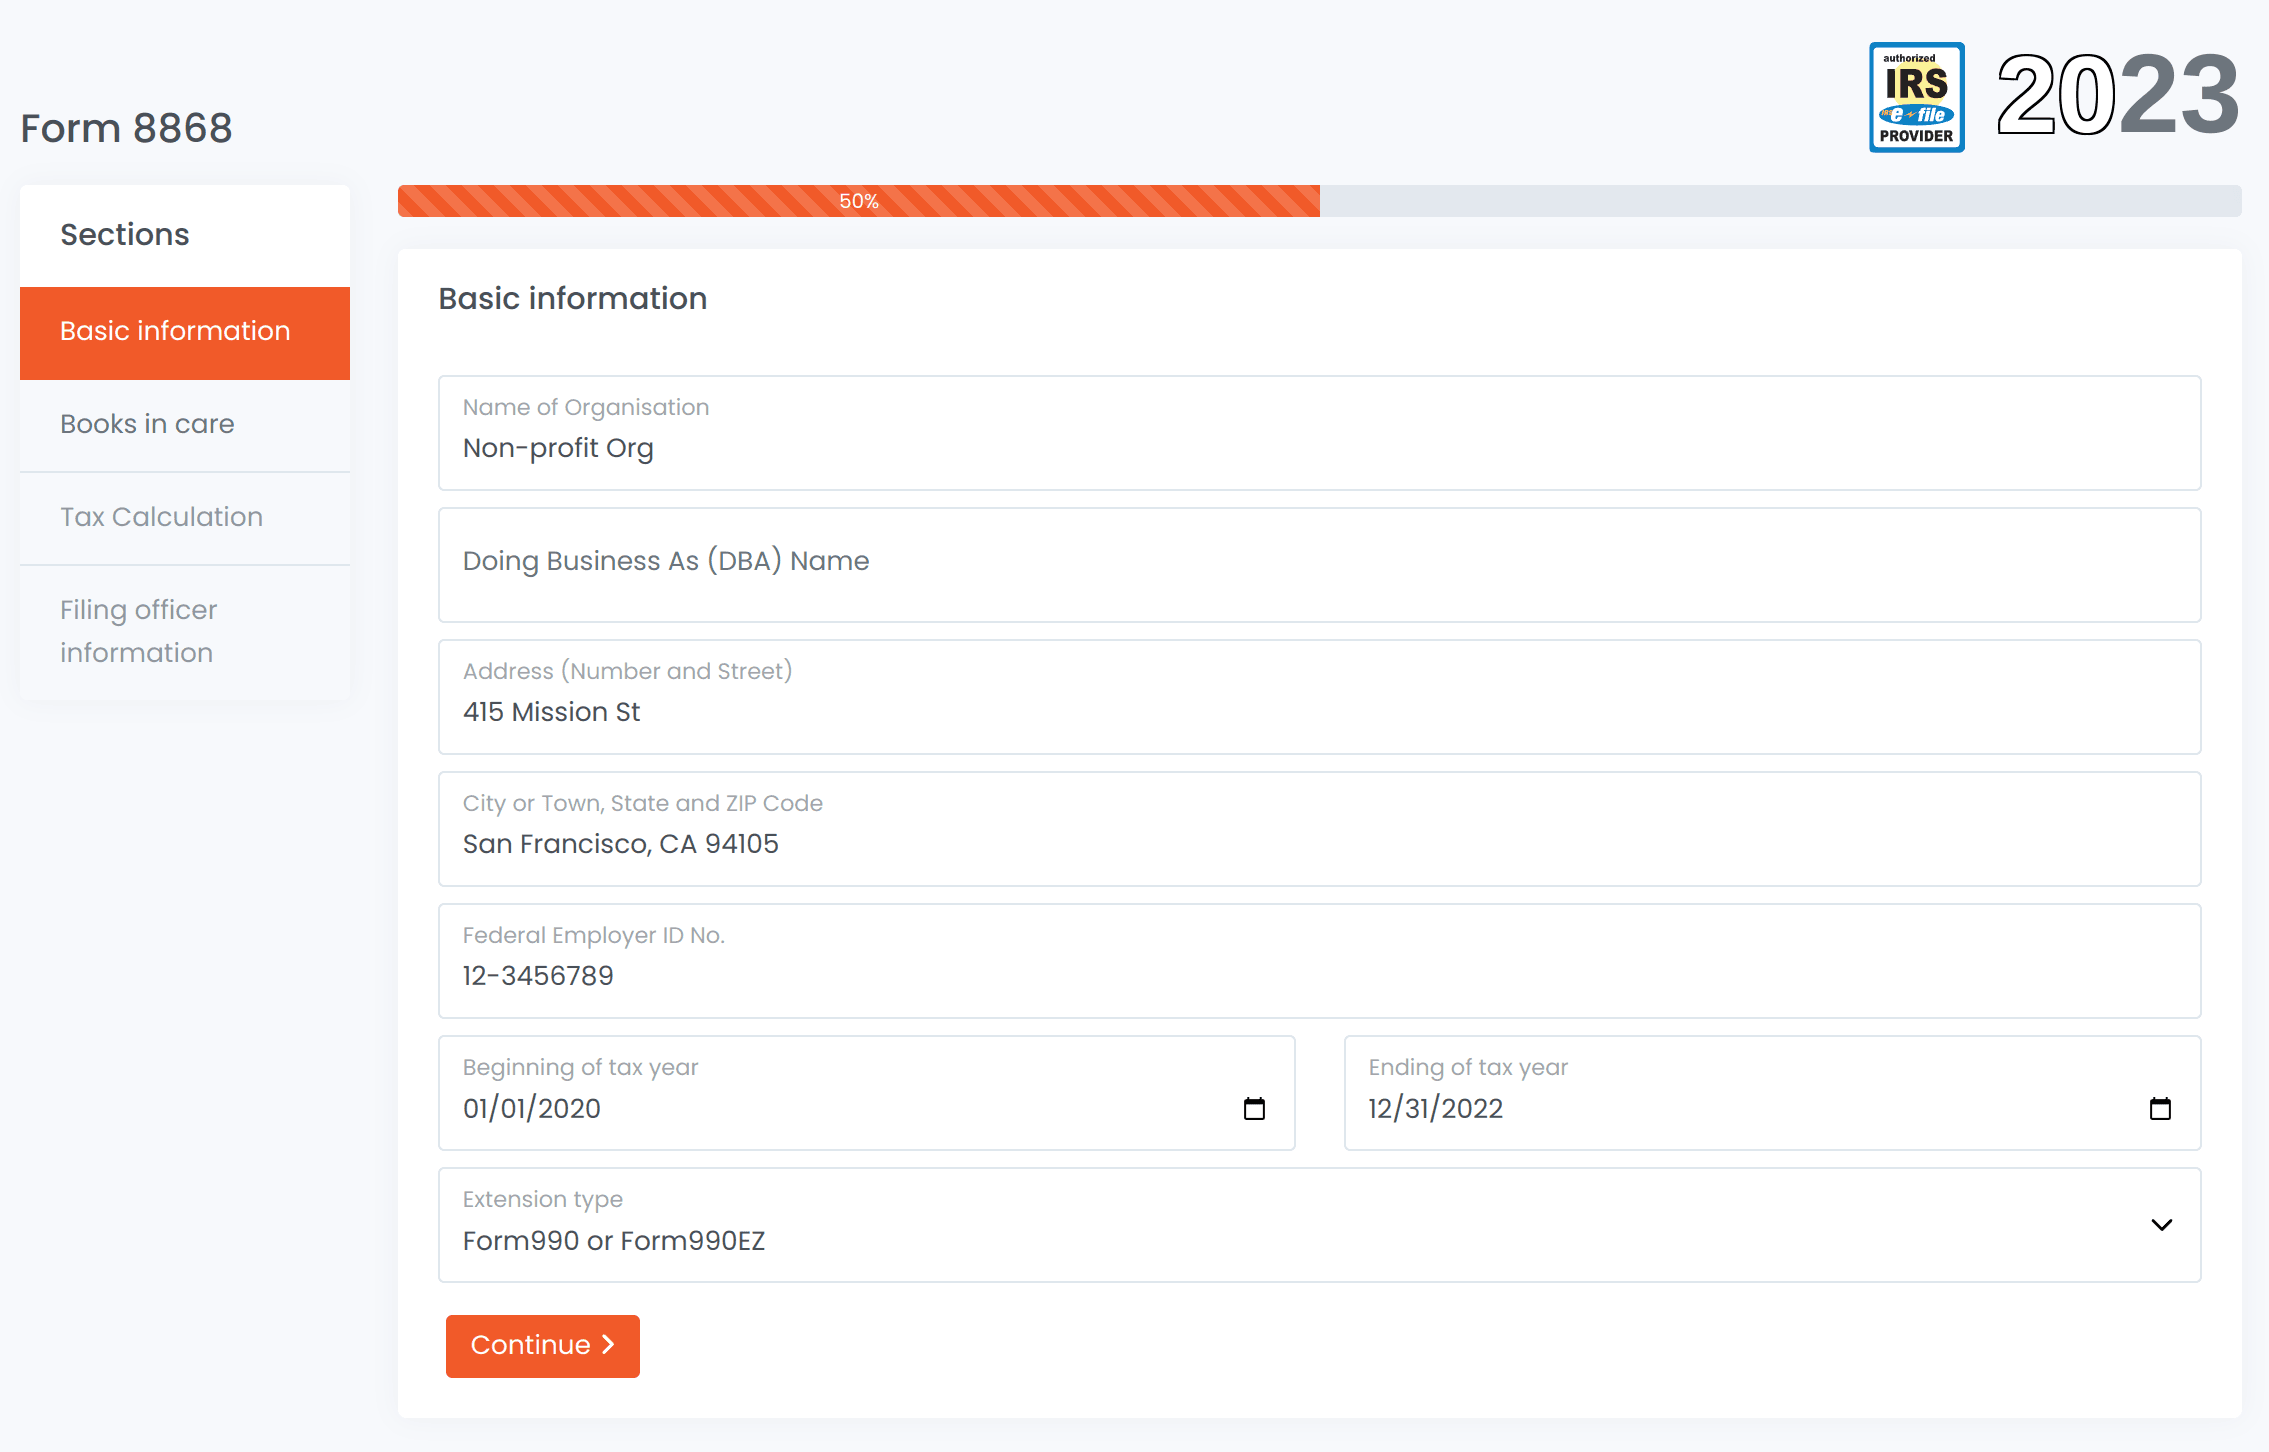
Enter the tax year dates carefully. The tax year on Form 8868 must be the same year as the return you plan to file. A calendar-year organization enters January 1 to December 31. A PTA with a July 1 to June 30 year enters those dates.
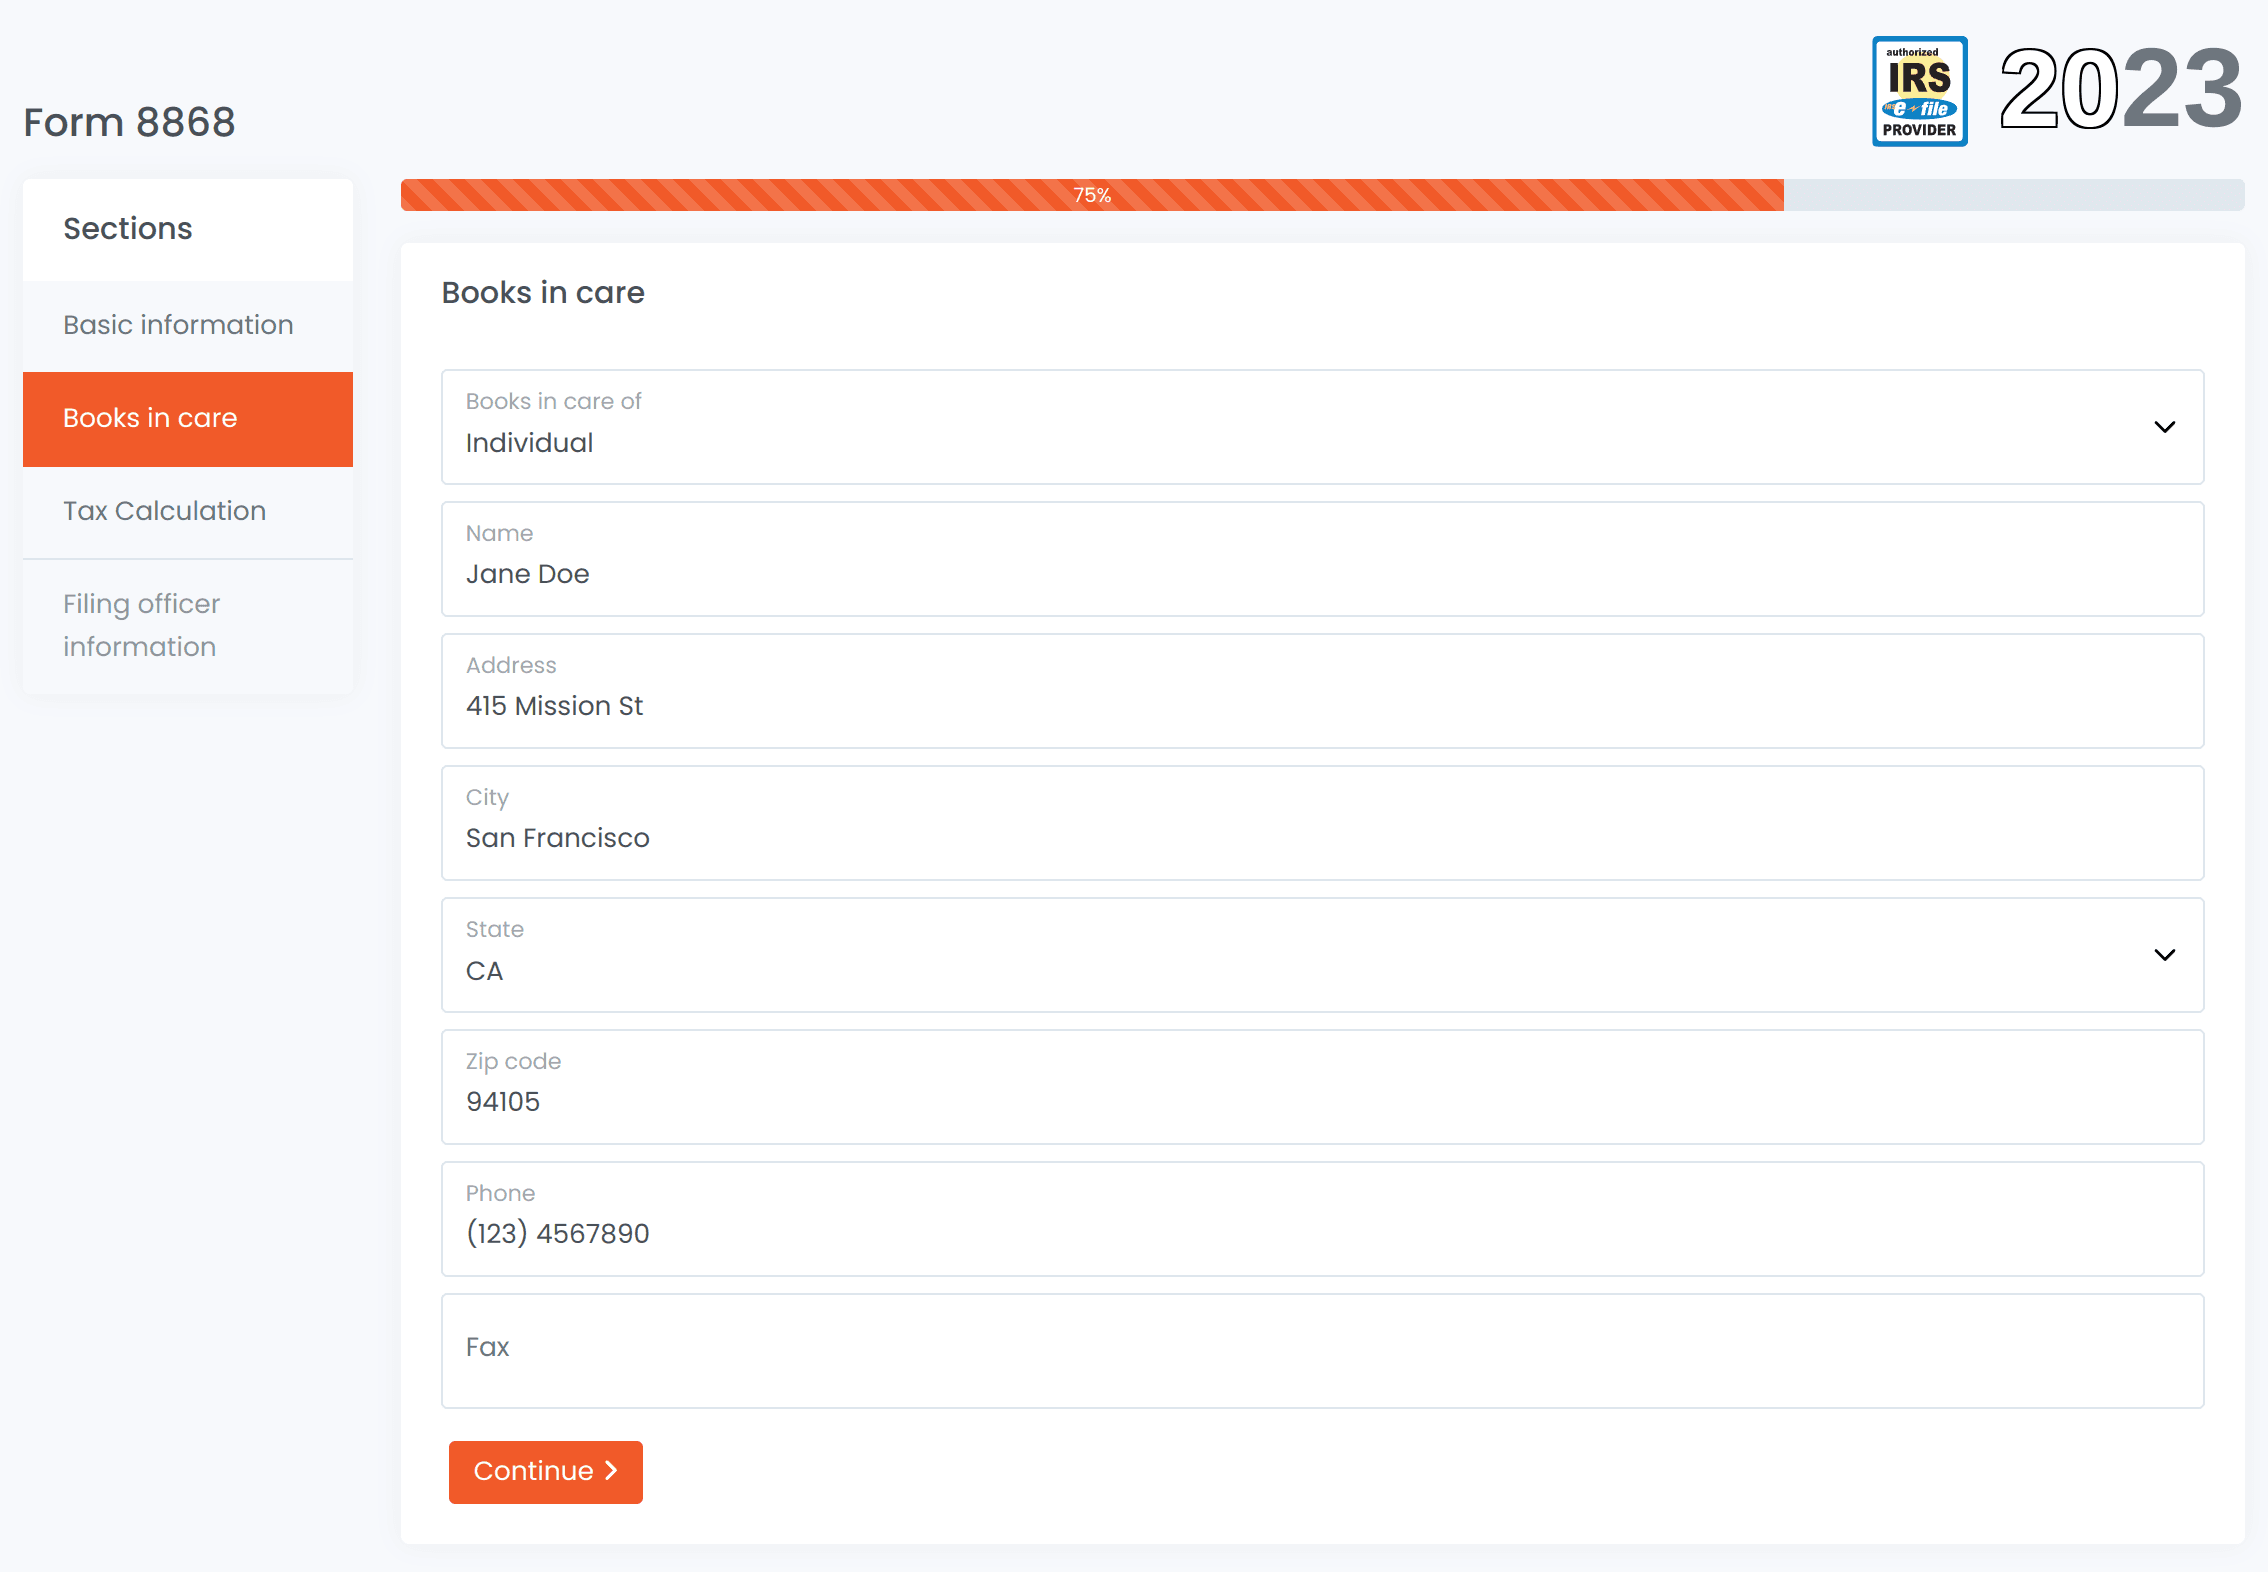
Step 3: Books in care of. Enter the person who keeps the organization's books and records, with a phone number. This tells the IRS whom to contact.
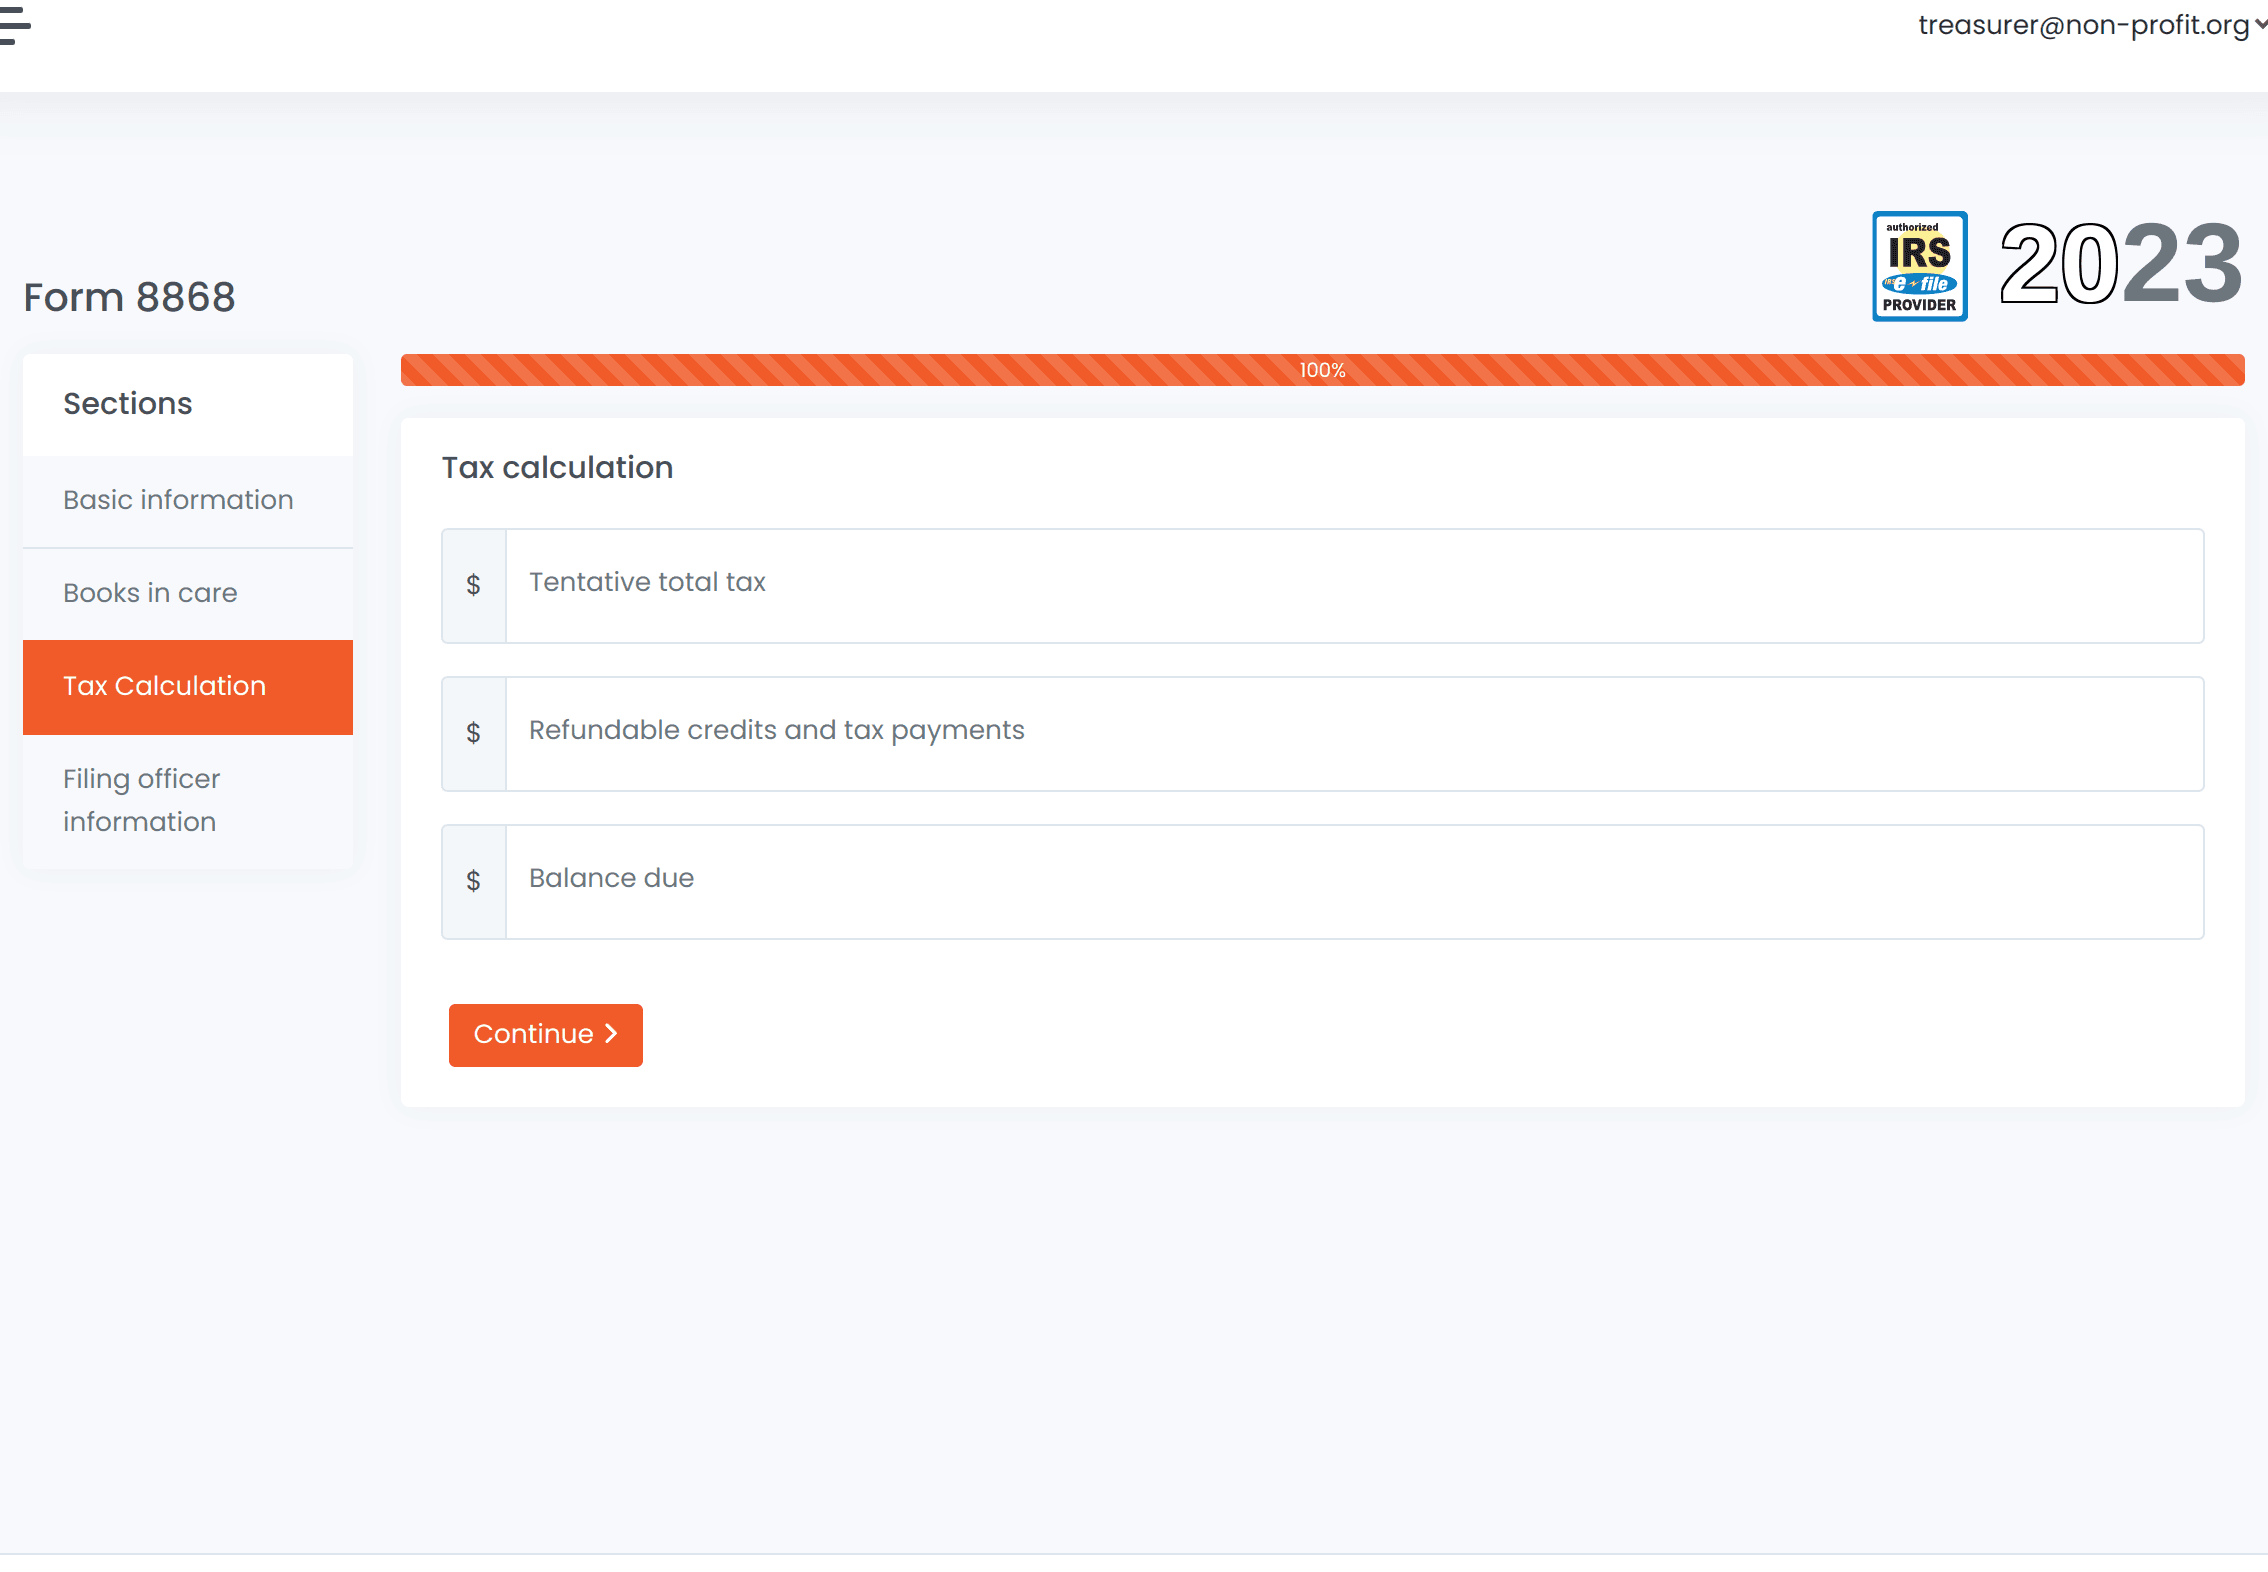
Step 4: Tax calculation. Part II of Form 8868 asks for tentative tax, payments already made, and the balance due. The IRS grants the automatic extension only if you file on time and pay any balance due shown on Part II, line 3c, by the return's due date. If the return you are extending will show no tax, these amounts are zero.
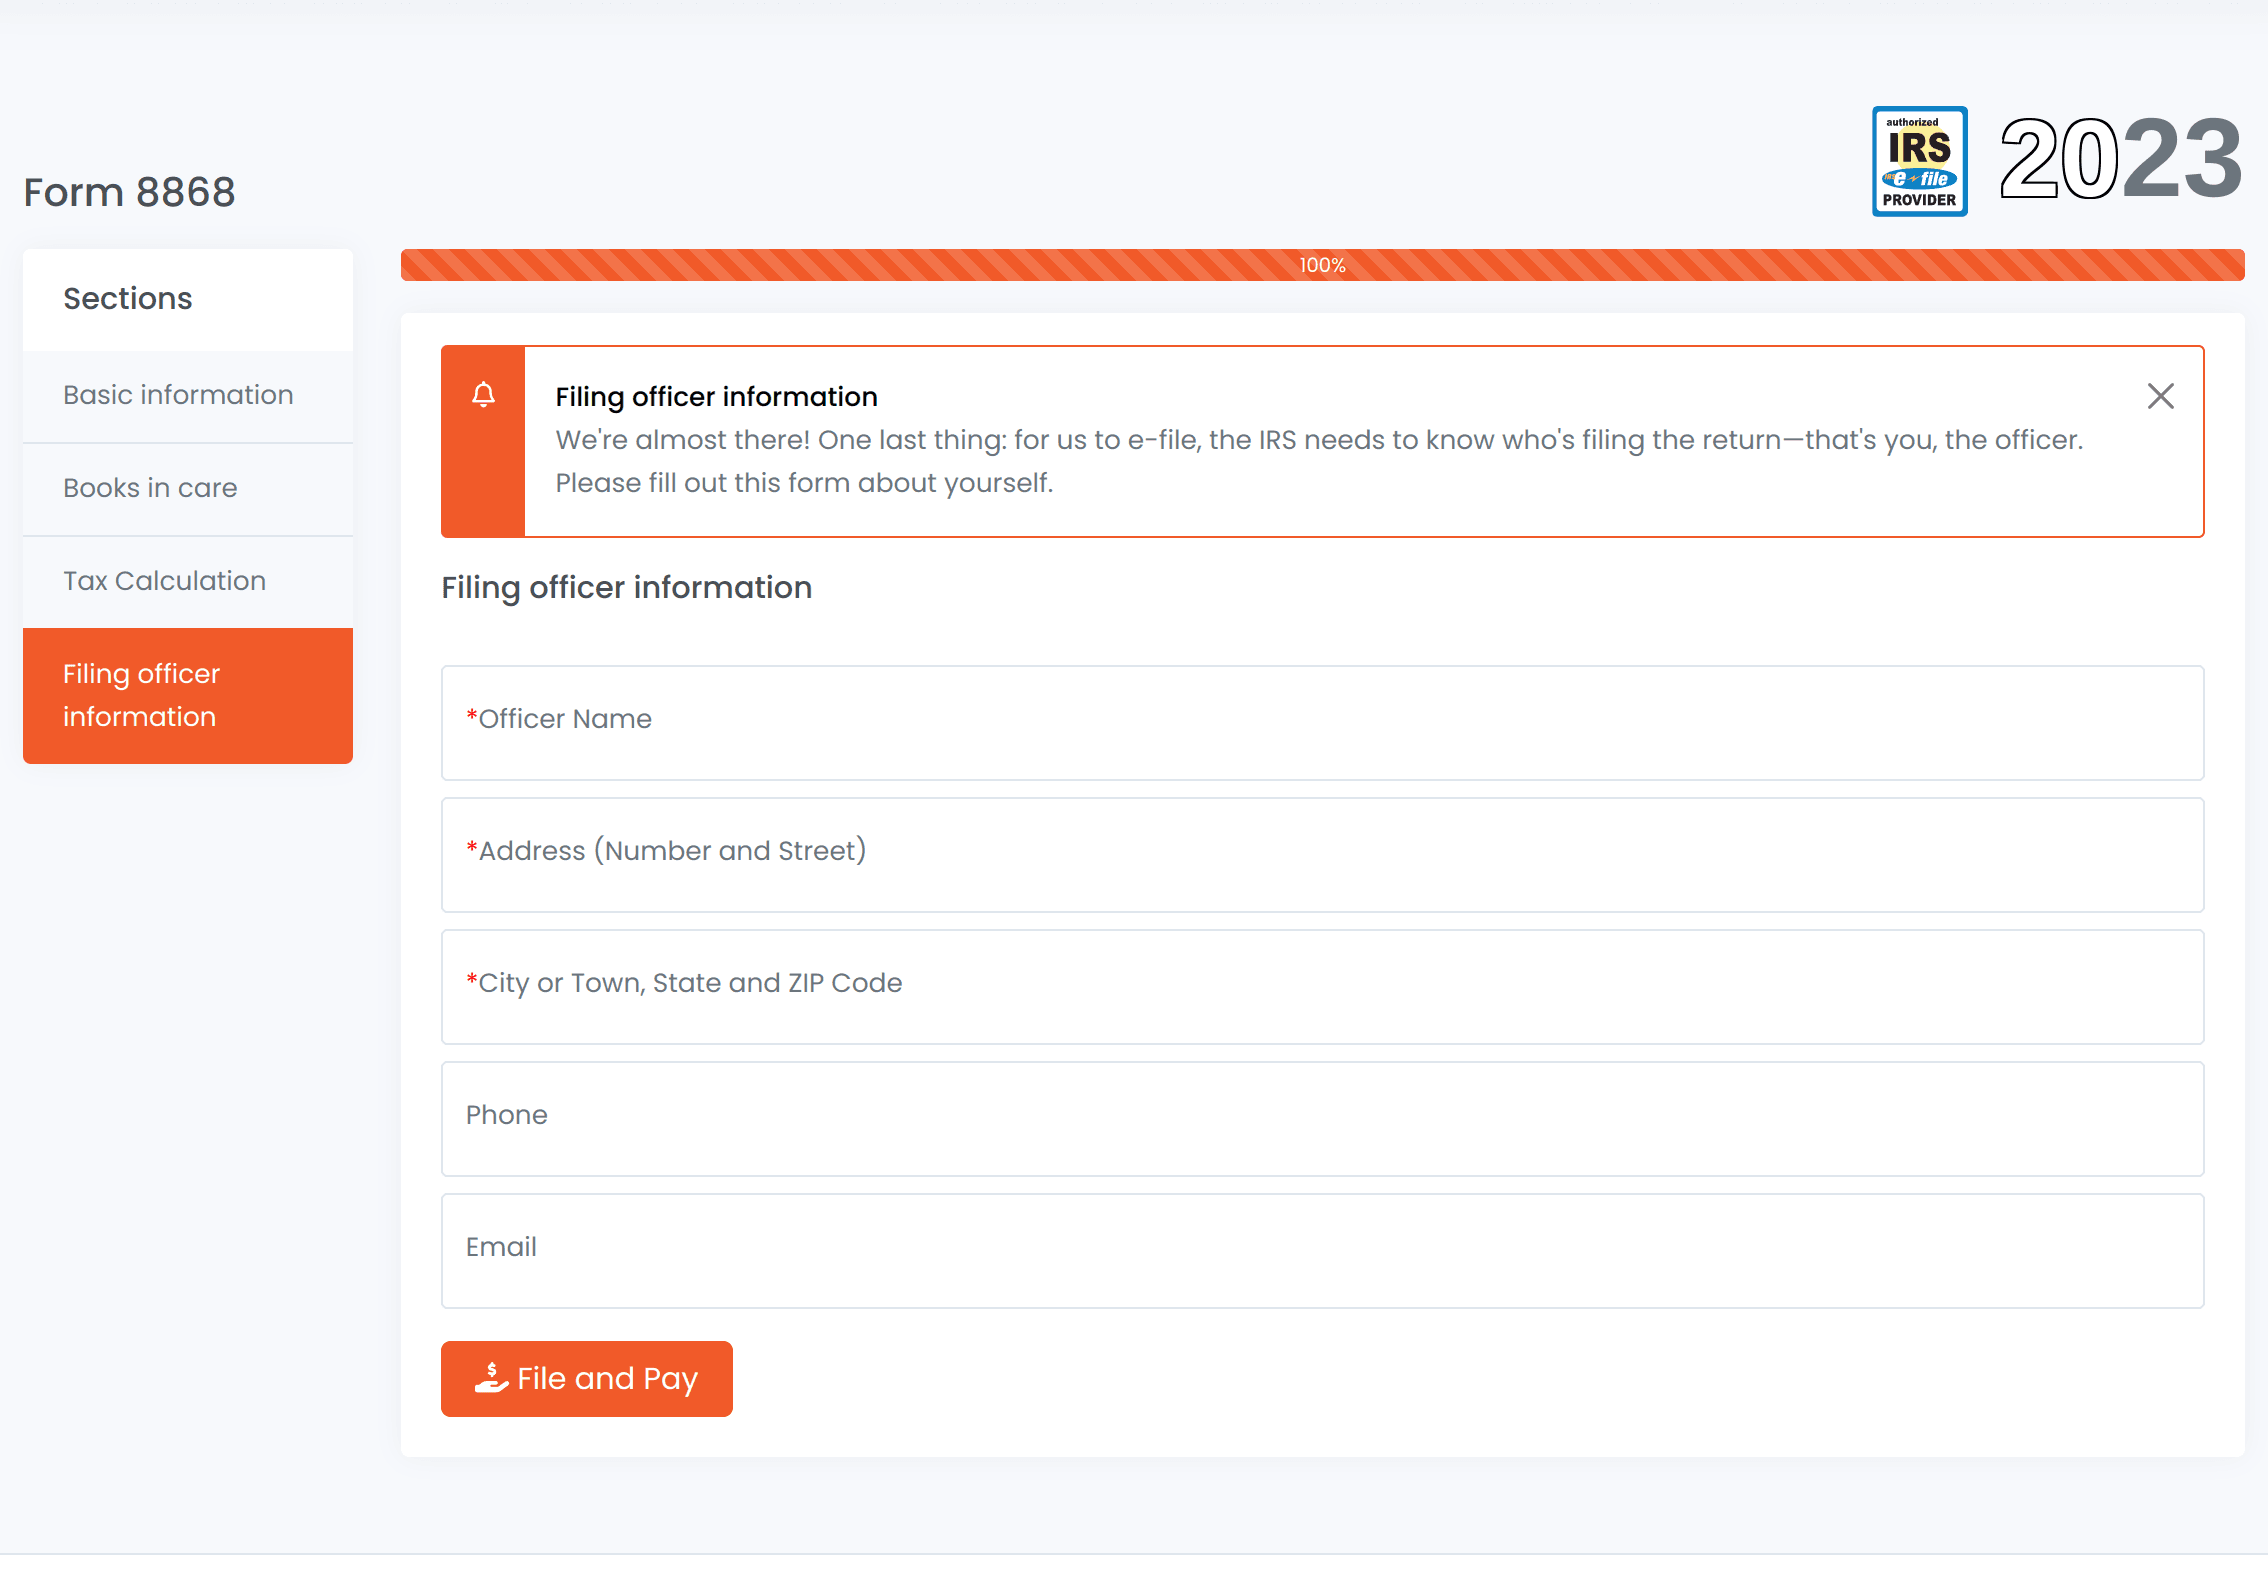
Step 5: Filer information. Enter your name, title and contact details as the officer or authorized person filing for the organization.
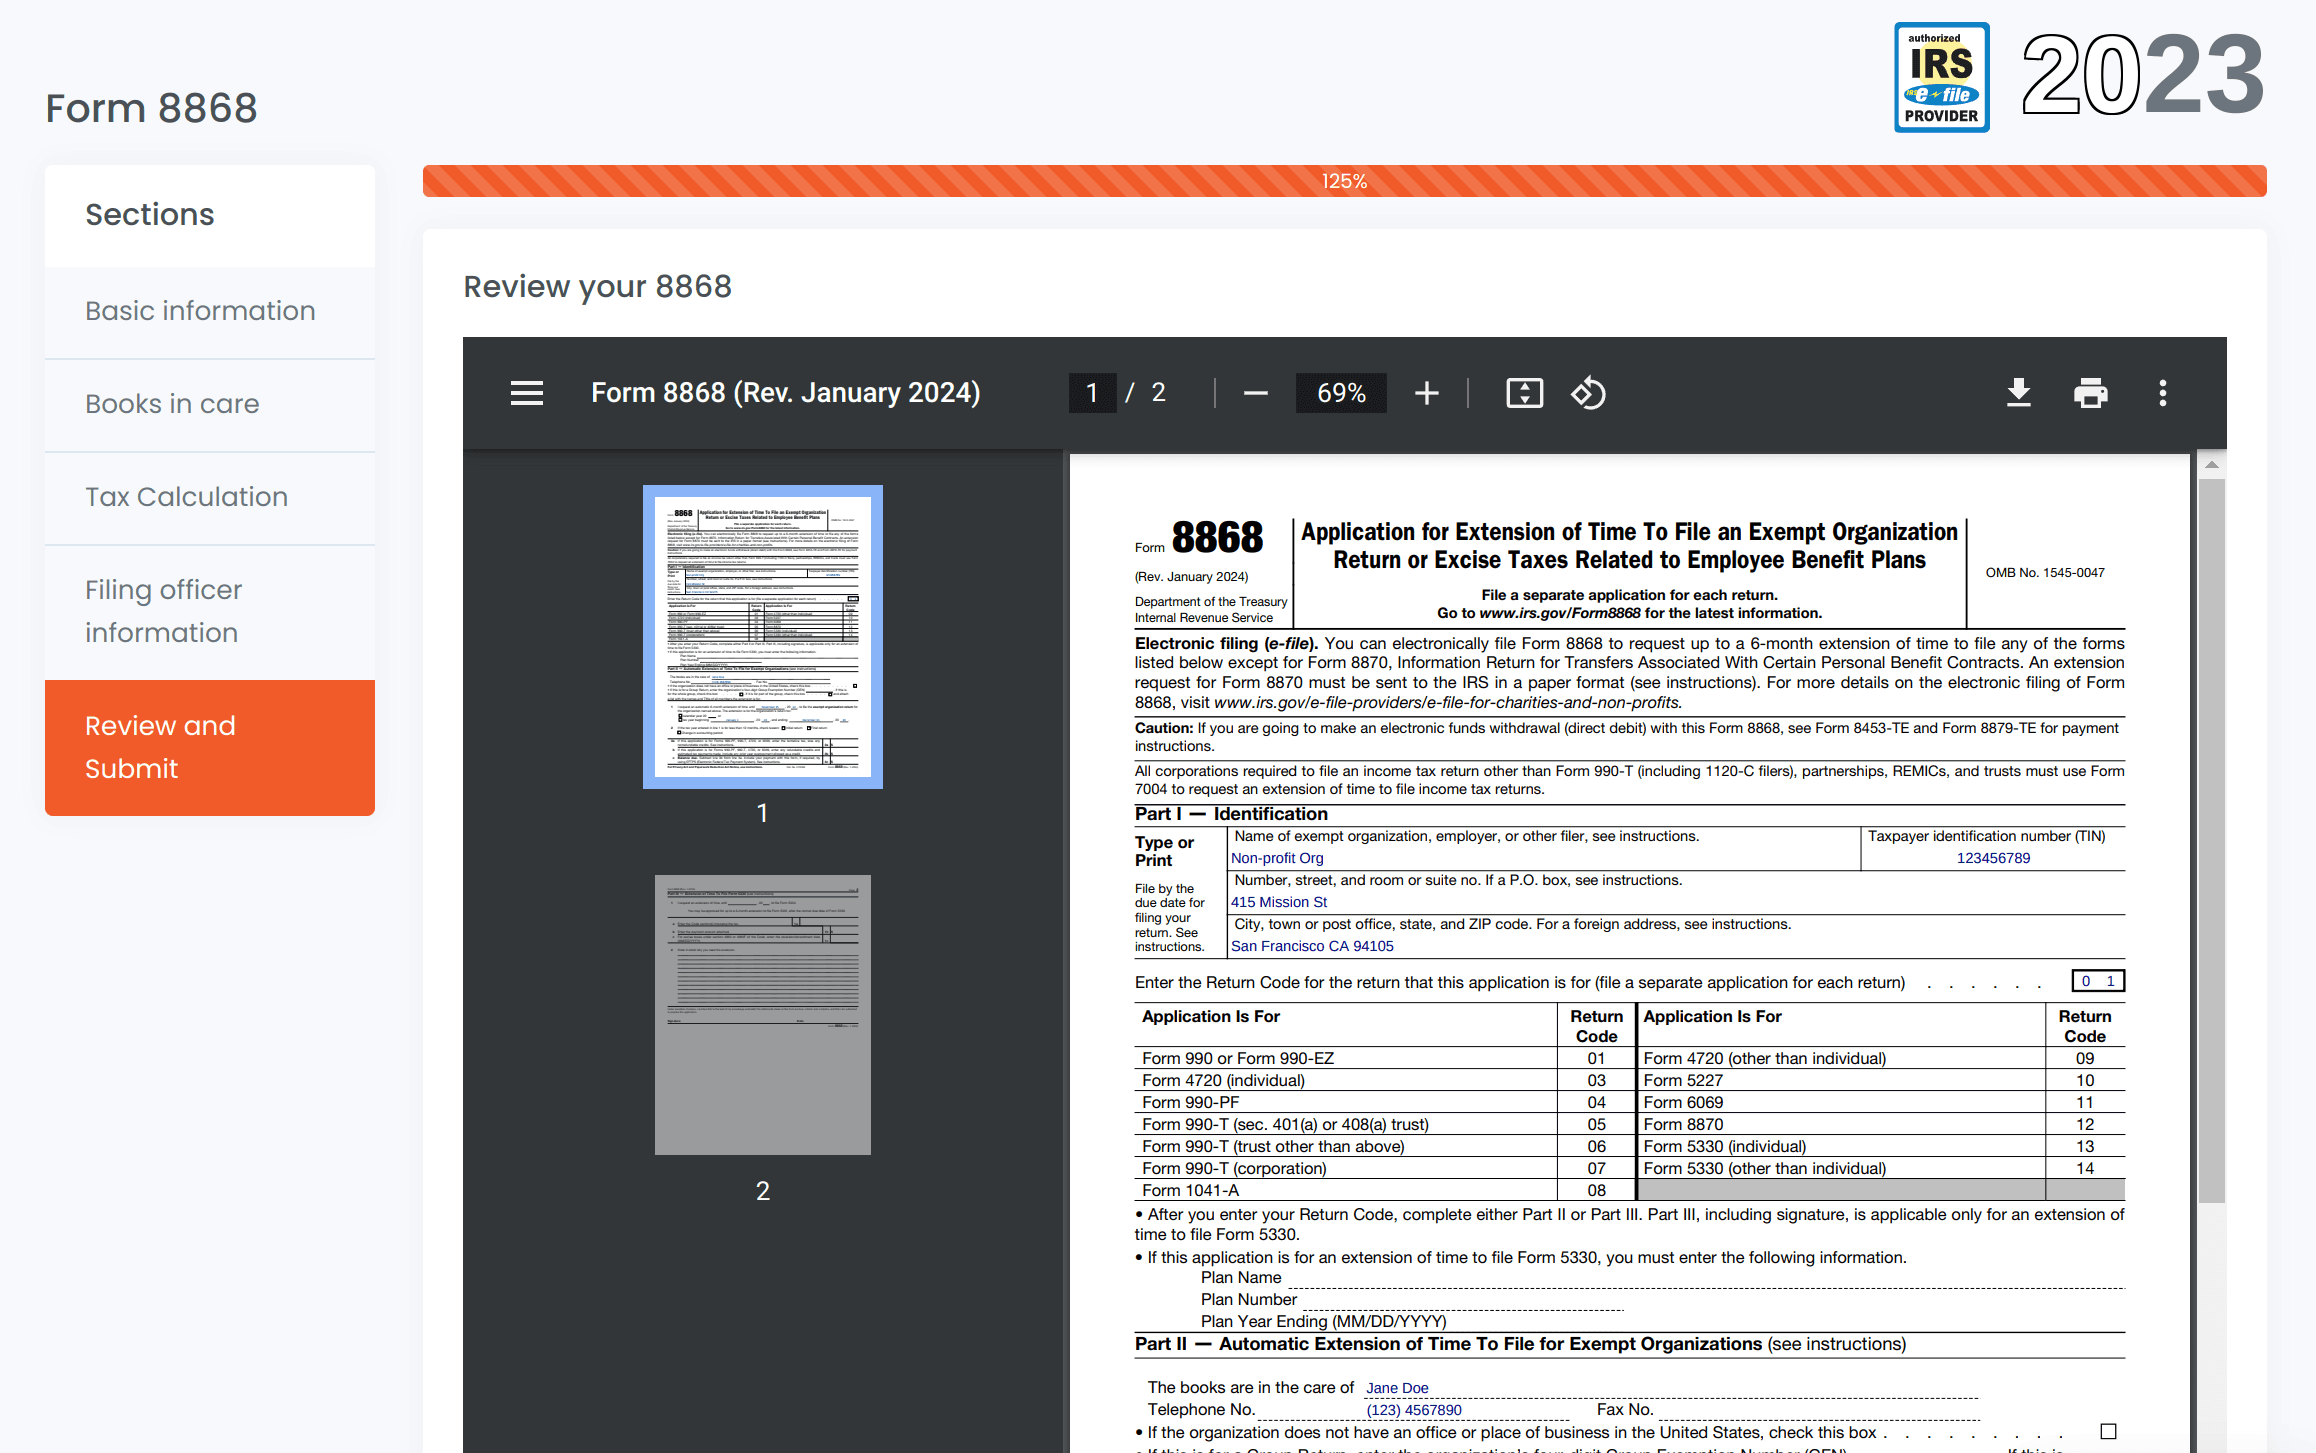
Step 6: Review. Read the completed form. Check the EIN, the tax year dates and the return being extended.
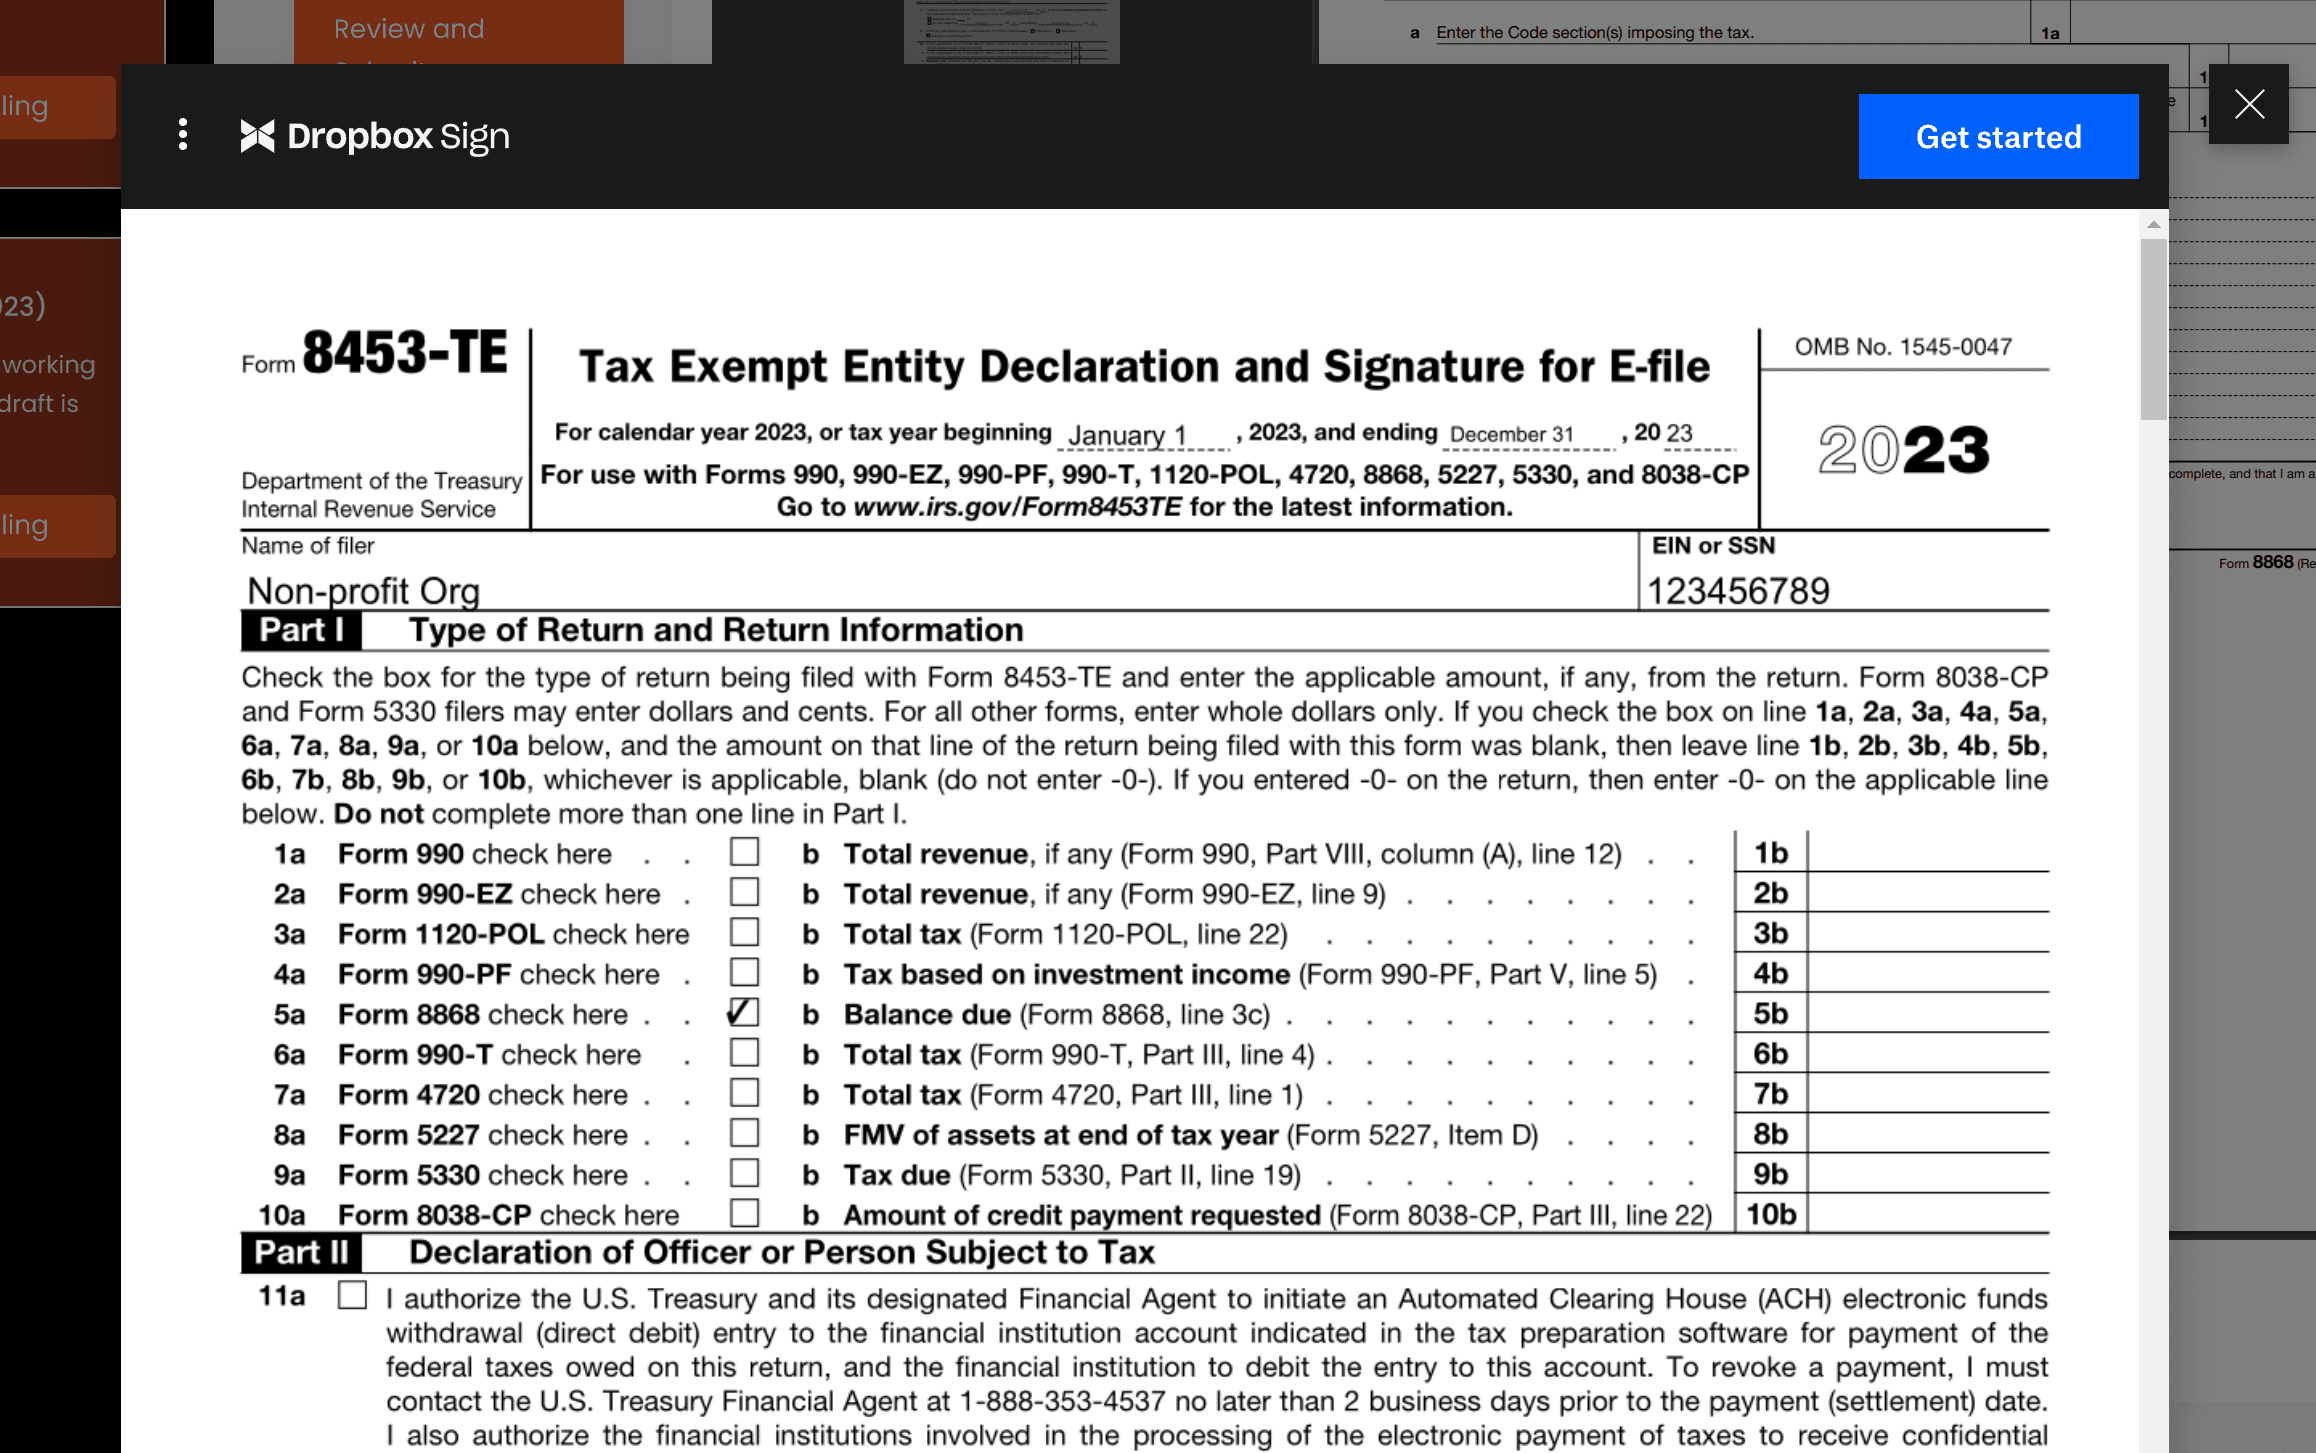
Step 7: Sign Form 8453-TE. Form 8453-TE is the IRS "Tax Exempt Entity Declaration and Signature for Electronic Filing". The IRS lists Form 8868 among the forms it authenticates. By signing, you authorize 990.tax to transmit the extension for your organization.
Step 8: Pay and transmit. Pay the $9.99 fee. 990.tax then sends Form 8868 to the IRS.
Step 9: Watch for the result. You get an email from [email protected] when the IRS accepts or rejects the extension. Keep the acceptance email and a copy of the form with your records. If it is rejected, correct the problem and resend before the due date.
After the extension is accepted
Your return is now due six months after the original due date, adjusted for weekends and holidays. For a calendar-year 2025 return, that is November 16, 2026. For a June 30, 2026 year end, it is May 17, 2027, because May 15, 2027 is a Saturday.
When the books are done, file Form 990-EZ with 990.tax ($89.99). 990.tax does not file the full Form 990 or Form 990-PF.
If you file after the extended due date, late-filing penalties can apply. The 2025 Form 990-EZ instructions list $25 a day, up to the lesser of $13,000 or 5% of gross receipts, unless you show reasonable cause.
Questions can go to [email protected].
Disclaimer: This post is for general information and is not legal or tax advice.